This study aims to comprehensively map and prioritize risks in the pharmaceutical supply chain, focusing on European and North American countries through a multi-actor perspective.
Through a structured literature review on supply chain risk management in the pharmaceutical supply chain, we identified 84 risks. After shortlisting the 15 most critical ones, we applied the analytic hierarchy process to prioritize risks affecting the pharmaceutical supply chain, considering both the perspective of individual actors and the entire supply chain.
This study first analyzed the pharmaceutical supply chain risk management literature to identify the most critical risks. It then offered a novel perspective on risk prioritization through a multi-actor analytic hierarchy process, revealing how different actors assign varying levels of priority to these risks based on their unique roles and business contexts.
Recent disruptions, such as COVID-19 and the Ukraine conflict, reshaped pharmaceutical supply chain risk priorities, revealing a ranking that diverges significantly from the literature. Each supply chain actor prioritized risks differently based on their role, highlighting a fragmented approach and emphasizing the need for more collaborative, systemic risk management. This study introduces new research directions to address unmet, real-world needs within pharmaceutical supply chain risk management.
Introduction
Pharmaceutical supply chain (PSC) distinguishes itself from other manufacturing supply chains (SC) because of its urgency, relevance, storage and transportation safety requirements and regulation (De Vries et al., 2021; Moktadir et al., 2018). The COVID-19 pandemic disrupted global SCs, due to surging demand and uncertain decision-making (Browning et al., 2023; Strong et al., 2020). PSC already adjusting for Brexit had to further refine its strategies (Roscoe et al., 2020). However, this was merely the first wave of disruptions, followed by the global chip shortage, the war in Ukraine, the Suez Canal blockage, rising inflation, the energy crisis and the conflict in the Middle East. In this context, managing SC risks is increasingly challenging (Alicke and Strigel, 2020), intensifying the need for robust risk management practices in PSC (Chowdhury et al., 2021; Van Hoek and Loseby, 2021).
This study explores major risks affecting the PSC and how stakeholders prioritize them. It focuses on risk identification and assessment, evaluating potential impacts to determine the most critical risks. It addresses two main limitations in prior research: the lack of a comprehensive overview of PSC risks and the changed perspective on risk prioritization (Da Silva et al., 2020).
Most literature on risk prioritization focused on a few risks or specific regions in the pre-COVID-19 stable environment (e.g. Moktadir et al., 2018). In addition, earlier literature targeted risks like shipping delays and exchange rate fluctuations. However, post-COVID-19, the most impactful risks are raw material (RM) shortages and insufficient manufacturing capacity (Guntuka et al., 2024; OECD, 2024).
This research offers a comprehensive view of PSC risks and their relative importance, exploring changed risk perceptions in the current environment. It examines how different PSC players evaluate and prioritize risks based on their network position, considering how their specific business and role influence perceptions. The investigation is guided by two research questions:
What are the risks affecting the PSC?
How do different PSC actors prioritize these risks?
This study not only addresses these research questions but also seeks to identify strategic directions that extend beyond immediate answers to inspire further research and pathways.
Methodology
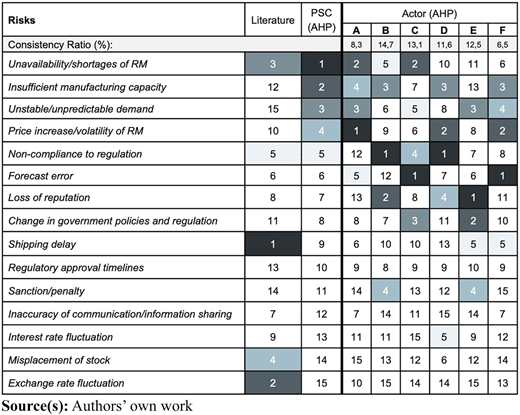
Analytic hierarchy process (AHP) is a widely adopted methodology for risk assessment and prioritization (Ammarapala and Luxhøj, 2007; Enyinda, 2017; Ganguly and Guin, 2013). We first identified 84 risks affecting the PSC, by homogenizing the academic literature at the intersection of supply chain risk management (SCRM) and PSC, focusing on articles published in management journals in this century. Then, we shortlisted the 15 most critical ones starting from the rankings of eight key papers performing a prioritization of PSC risks, ensuring compatibility with the AHP. Then the AHP was run, and experts were asked to compare these risks using the Saaty Scale (1–9), answering: “How much more important is the impact of risk i on the continuity of your business compared to risk j when it occurs?” A consistency test is needed to normalize inconsistent judgments, so the consistency ratio (CR) was calculated and reported in Figure 2, with a 15% cut-off threshold. Once all judgments were recorded and the CR threshold verified, these were aggregated using a geometric mean, which consolidated the experts’ assessments into a single matrix. This matrix reflects the relative importance of each risk, with values indicating how much more impactful one risk is compared to another. The software then converted these values into percentages to establish the final ranking, with higher percentages indicating greater perceived importance.
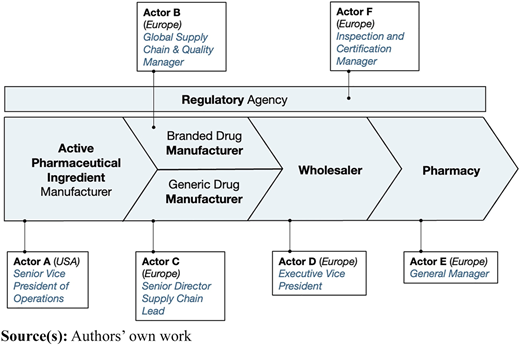
We adopted a purposive sampling method (Emmel, 2013) to engage information-rich respondents capable of addressing the research questions. Data were collected between February and March 2022, during the second wave of COVID-19 and the onset of the Ukrainian war, capturing real-time shifts in risk perception amid concurrent global disruptions. To grasp diverse perspectives, heterogeneity in sampling was perused, involving multiple respondents with relevant seniority from European or American organizations (see Figure 1).
Results
The first contribution of this study lies in the identification of evolving risk priorities driven by the crucial historical time capturing the second wave of COVID-19 and the Ukrainian war. Indeed, recent disruptions have reshaped risk perceptions, re-elevating the urgency of risks like RM shortages and regulatory compliance, as shown in Figure 2.
The most critical risk identified by the experts was the unavailability/shortages of RM. This risk was ranked high even in the literature ranking as the pharmaceutical industry is highly dependent on active pharmaceutical ingredient (API) manufacturers to produce drugs, which are limited in number and overwhelmed by difficult challenges that are affecting their growth (Schenck et al., 2024). Additionally, the pandemic and geopolitical conflicts have further exposed vulnerabilities in the SC affecting RM, raising its ranking position (Busby et al., 2021).
The issue of insufficient manufacturing capacity has also emerged as a significant bottleneck. The PSC has always been heavily influenced by manufacturing capacity constraints because of various factors, including demand uncertainty, production constraints and technological limitations (Cannella et al., 2008). However, manufacturing capacity is even more stressed during crises. Therefore, the COVID-19 pandemic increased its position in the ranking.
Unstable/unpredictable demand ranked third, highlighting the challenge of accurately forecasting demand and the vulnerability of PSC to sudden demand shifts. The pandemic’s panic buying enhanced the significance of this risk with respect to the literature ranking, highlighting how an increased demand, if not compensated by an increase in capacity, could cause periodic shortages that can be dangerous for patient health (Strong et al., 2020).
Upon analyzing the collective viewpoint of the six principal actors within the PSC, this research also explores how different PSC actors prioritize risks, as indicated in Figure 2.
API producers viewed price increase/volatility of RMs as top risks. Indeed, as witnessed by Actor A: “There is substantial fluctuation in the cost of these materials, which complicates business management, especially when prices have already been agreed upon with customers. Such volatility can destabilize our business operations, as it is often difficult to absorb these cost fluctuations without impacting financial stability”. These inflationary pressures were compounded by recovery efforts following COVID-19, which strained PSC and lifted prices. Experts also emphasized the challenge of delivery schedule adherence over market availability of RMs and noted the pandemic-induced demand surges as a significant disruption. Moreover, the issue of unstable/unpredictable demand, especially due to the pandemic, disrupted the PSC, resulting in lost sales and potential negative impacts on patient health.
Pharmaceutical manufacturers prioritized non-compliance to regulations as their top risk due to its critical importance for public health and safety. Non-compliance can lead to severe consequences, including financial penalties and product recalls, significantly impacting revenue. Loss of reputation was also a major concern, as manufacturers aimed to protect their brand from recalls, legal issues and criticisms over inadequate transparency in clinical trials. Insufficient manufacturing capacity ranked third, with COVID-19 highlighting the challenges in scaling up production quickly to meet demand surges, threatening sustainable access to essential medicines.
Generic manufacturers, specialized in producing non-branded products, pinpointed forecast errors as the top risk, causing either excess inventory and financial issues or missed sales from underproduction. They also highlighted unavailability/shortages of RM. Indeed, increased demand for certain pharmaceuticals and macroeconomic disruptions have intensified raw material competition among manufacturers. This posed a significant challenge for generic manufacturers at risk of being outcompeted by branded companies due to narrower margins. Lastly, change in government policies and regulations prompted drug recalls, inhibiting sales and resulting in profit losses, as in the case of Forecast errors as reported by Actor D: “Forecast errors can have significant repercussions, leading to critical issues like compliance risks, stockouts, or excess inventory. These errors necessitate robust forecasting models that are sensitive to changes in market and regulatory environments to ensure product availability and compliance, thus safeguarding also company’s reputation”.
Wholesalers, intermediaries in the PSC delivering medicines to points of sale (pharmacies) or points of consumption (hospitals), identified non-compliance to regulations as the foremost risk threatening their operations. The withdrawal of non-compliant medicines disrupted the PSC, severely affecting their business. Additionally, the risk of price increase/volatility of RMs significantly impacted their business. Fluctuations in upstream manufacturing costs posed a threat to their high-volume, low-margin approach, raising concerns about sustainability and profitability. Insufficient manufacturing capacity ranked third, affecting wholesalers if manufacturers fail to meet demand, leading to order fulfilment challenges and inconsistent supply to endpoints. Production delays from capacity issues extended delivery times, complicating inventory management and the ability to promptly meet demand.
Pharmacies, the final distribution channel to patients, prioritized the loss of reputation as the primary risk. At the heart of pharmacy operations stands the imperative to ensure patient safety, as medication errors can be life-threatening, directly impacting trust in healthcare. Changes in Government policy and regulations led to the disappearance of medicines from the market, affecting sales and profit margins. New regulations can impact pharmacy operations, how drugs are dispensed and the financial model supporting pharmacy services. For instance, policies broadening the scope of pharmacy services, such as managing vaccines or COVID-19 tests, influenced both operations and profitability. Lastly, unstable/unpredictable demand posed a challenge due to its commercial nature, impacting profitability by affecting inventory management. Overestimating demand led to excess inventory and potential losses while underestimating results in stockouts, loss of sales and dissatisfied customers.
In this analysis, the final actors were the regulators, who supervise the whole PSC. Their commitment to drug safety and accessibility shaped the risk landscape. Regulators pinpointed forecast errors as the primary risk due to its essential role in meeting patient needs and facilitating drug access. This risk was particularly significant, as patient welfare is central to their mission. Subsequently, price increase/volatility of RMs was identified as the next critical risk. It affected equitable access to medicines, especially within public health systems. Lastly, insufficient manufacturing capacity was a notable risk, emphasized by COVID-19 and the immediate need for vaccine production. This risk highlighted the importance of a resilient PSC capable of meeting both routine and emergency healthcare needs, underlining the regulators’ role in promoting a responsive pharmaceutical supply framework.
The study of risk perception among PSC actors revealed a fragmented landscape, with each actor prioritizing risks based on their specific SC role. This fragmentation led to siloed risk management strategies focused on mitigating immediate business segment risks (Da Silva et al., 2020). Consistent with studies in Iran (Yousefi and Alibabaei, 2015) and Morocco (Benazzouz et al., 2020), these findings indicate a widespread lack of understanding of the importance of SCRM interconnectedness within the PSC. COVID-19 highlighted the pitfalls of this approach, causing care bottlenecks and extended patient waiting times. A collaborative approach to risk assessment and management would have improved PSC resilience and ensured a more consistent supply of medicine to patients.
Future research agenda
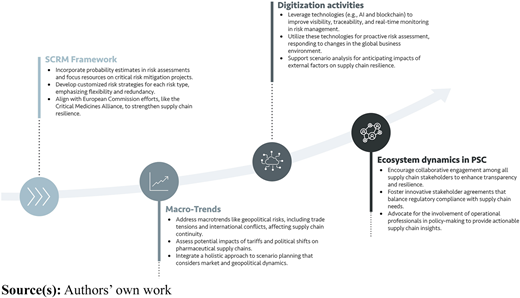
The findings of this study provide a practical foundation for advancing SCRM research. This section guides the scientific community, policymakers and stakeholders in prioritizing key challenges and seizing new opportunities. It identifies essential research areas and outlines steps to enhance knowledge, foster innovation and positively contribute to addressing industry and societal needs. We propose four main impact pathways, i.e. research directions, illustrated also in Figure 3.
To enhance the SCRM framework, it is recommended to complete risk assessments with probability estimations and comprehensive impact evaluations across both financial and societal dimensions (De Vries et al., 2021). By assessing the financial impact of various risk types, companies can better justify the necessary investments for mitigation and allocate limited resources to the most critical projects. Additionally, evaluating societal impacts, such as public health consequences, further underscores the importance of responsible risk management. Given that companies cannot invest in all risk mitigation initiatives simultaneously, a targeted approach is essential. Customized mitigation strategies should be developed for each type of risk, accompanied by a resilience strategy that incorporates flexibility and redundancy to strengthen the entire SC. The European Commission has recently taken steps to enhance PSC resilience, largely in response to the insufficient COVID-19 preparedness observed within the European Union (EU). Among these efforts is the establishment of the Critical Medicines Alliance [1] (CMA), whose primary objectives include identifying a list of critical medicines and assessing SC vulnerabilities. The CMA’s methodology begins with the selection of medicines from the Union List of critical medicines that experienced shortages, as notified to the European Medicine Agency (EMA) between 2019 and 2023. This initial selection is followed by a ranking process based on quantitative criteria, where the risk of SC disruption is evaluated using the total number of past and ongoing shortage notifications per medicine between 2019 and 2023. In a third phase, the medicine list is refined further by incorporating qualitative factors, including manufacturing specifics, geographic sourcing, single versus multi-sourcing arrangements, location of API suppliers (within the EU or from third countries), aseptic processing requirements, storage needs and transportation challenges. Nevertheless, this approach demonstrates limited rigor in incorporating qualitative data, and its focus on single molecules as the unit of analysis restricts a broader view of SC risks. Consequently, this single-molecule focus provides insights into the molecule’s characteristics but does not fully capture the unique aspects and vulnerabilities of its SC. Therefore, we propose that future research should explore points of intersection with the CMA and offer enhanced methodological guidelines for risk identification and assessment in PSC. This will allow for a refinement of the methods currently used by the European Commission within the CMA framework, as well as the introduction of the Health Emergency Preparedness and Response Authority (Wouters et al., 2023).
This study demonstrates how the pandemic has reshaped risk prioritization within the pharmaceutical industry, signaling a shift from the preexisting literature (see Figure 2). While the pandemic had a substantial impact, it was not the only disruption affecting modern SCs. For instance, our data collection took place between February and March 2022, a period that spanned the declining phase of the pandemic and the onset of the war in Ukraine, both significant events in the reorganization of global SCs. In this context, exploring macrotrends is essential for a comprehensive approach to SCRM. The future of PSC risk management depends on integrating these trends to enhance scenario identification and mitigation. Indeed, an effective risk management strategy must account for all large-scale changes affecting SC continuity (Zhu et al., 2024). The first step is to analyze current trends impacting the market, with a particular focus on the implications of geopolitical risks, such as trade tensions, political instability and international conflicts. Since these factors pose threats to PSC business continuity, it is then critical to assess the potential impacts of tariffs or sanctions on pharmaceuticals and to keep track of political developments influencing international trade relations.
The availability of data in the PSC has significantly increased due to various public and private digitization initiatives. The European Union’s Falsified Medicines Directive (EU FMD) plays a key role, particularly through the provision of safety features. Alongside this, the European Medicines Verification Organization (EMVO) enforces strict drug traceability guidelines and supports the implementation of the EU’s first digital traceability system for human medicines (Farinelli et al., 2023). Although these systems have laid an essential foundation, their potential for SCRM is not yet fully utilized. Furthermore, the rapid evolution of emerging technologies like artificial intelligence, Internet of things and blockchain that improve visibility, traceability and real-time monitoring, open a new avenue for strengthening SCRM in PSC (Li et al., 2023; Xiong et al., 2021). Indeed, these tools can support a dynamic and proactive risk management approach, responsive to shifting priorities in the global business environment (Li et al., 2022), that anticipates future risks and considers external factors like consumer trends and sociopolitical changes (Aboutorab et al., 2022; Baryannis et al., 2019). While promising, these solutions still require effective integration, a clear demonstration of their real-world benefits and further development to address the practical challenges in achieving widespread adoption, creating the need for further research.
This study reveals a compartmentalized view of risks within the pharmaceutical industry, characterized by a siloed perspective that impedes a systemic and collaborative SCRM approach. However, the highly regulated nature of the PSC requires the presence of collaborative platforms that can form the basis to successfully engage the full stakeholder ecosystem. The EU FMD is an example of it, where coordination across PSC stakeholders has already proven successful, showing that specific methods of collaboration are key to drive action and reflections along the SC, enabling full engagement and a holistic SC view.
Future research should therefore explore the advantages of connecting various SC partners to enhance SCRM and industry resilience (Kuo et al., 2021). Stakeholder engagement is vital for building resilience within complex, highly regulated SCs like those in the pharmaceutical sector. Successful engagement relies on stakeholders’ innovativeness and their ability to create unconventional agreements that adhere to industry regulations (Li et al., 2023; Sharma et al., 2023).
This also serves as a call to action for policymakers, encouraging them to include genuinely relevant stakeholders in their initiatives. For instance, in the Assessment of the supply chain vulnerabilities for the first tranche of the union list of critical medicines [2], published in June 2024, the EU Member States, industry associations, the EMA, and other commission services were involved in creating the shortlist of 11 molecules with vulnerable SCs. While these agents provide a valuable governance perspective, the critical SC insights were missing: this operational experience can only come from on-the-ground professionals, such as those involved in our study.
Conclusions
This study captures a holistic view of the PSC, a highly concentrated industry where a limited number of key players, high R&D costs and intellectual property protections drive market concentration and consolidation (Kesic et al., 2015; Kyle, 2016). By including all major actors and applying a structured AHP with rigorous consistency checks, our findings provide a robust and representative analysis of evolving risk priorities in response to global shifts and crises. The contributions of this study are twofold. First, it advances the literature by adopting a multi-actor perspective and focusing on the European and North American contexts, considering their unique economic, political and geographical factors. More importantly, this study identifies and opens new impact pathways: strategic research directions aimed at addressing emerging challenges and unmet needs in PSC risk management. These pathways will guide future studies toward research that addresses key areas such as the improvement of the SCRM framework, emerging technologies, the impact of macro-trends and the creation of an ecosystem-wide perspective within the PSC. Proposed research directions aim to build a more interconnected and resilient PSC that can better respond to evolving risks.
However, this study has also some limitations, which are those inherently tied to this methodology. Although AHP is widely used for multicriteria decision-making, it demands considerable effort for pairwise comparisons, which can be time-consuming for decision-makers, particularly in complex scenarios (Rodrigues De Oliveira and Duarte, 2024). Additionally, AHP’s reliance on expert judgments brings a degree of subjectivity and potential bias.
This study was carried out within the MICS (Made in Italy – Circular and Sustainable) Extended Partnership and received funding from the European Union Next-Generation EU (PIANO NAZIONALE DI RIPRESA E RESILIENZA (PNRR) – MISSIONE 4 COMPONENTE 2, INVESTIMENTO 1.3 – D.D. 1551.11-10-2022, PE00000004). This manuscript reflects only the authors’ views and opinions, neither the European Union nor the European Commission can be considered responsible for them.