
1-20 of 5901
Keywords: LIBOR
Close
Follow your search
Access your saved searches in your account
Would you like to receive an alert when new items match your search?
Journal

Covering both finance and the intersection between finance financial markets and economics.
Journal Articles
Journal:
Studies in Economics and Finance
Studies in Economics and Finance 1–26.
Published: 25 September 2026
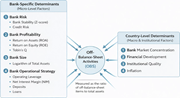
in Determinants of off-balance-sheet activities in banking: evidence from a cross-country panel
> Studies in Economics and Finance
Published: 25 September 2026
Figure 1. Bank-specific and country-level determinants of off-balance-sheet activities A diagram links bank-specific and country-level determinants to off-balance-sheet activities, measured as the ratio of off-balance-sheet items to total assets. The diagram places off-balance-sheet activities... More about this image found in Bank-specific and country-level determinants of off-balance-sheet activitie...
Journal Articles
Journal:
Studies in Economics and Finance
Studies in Economics and Finance 1–28.
Published: 21 September 2026
Includes: Supplementary data
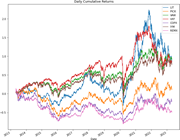
in Energy market and carbon emission spillovers in critical minerals investment: a dynamic connectedness approach
> Studies in Economics and Finance
Published: 21 September 2026
Figure 1. The daily cumulative return of portfolios for critical minerals Note(s): Cumulative returns are calculated by compounding daily log returns over the sample period to visualize long-term performance trends. While the TVP-VAR model uses daily first-differenced log-returns to ensure stat... More about this image found in The daily cumulative return of portfolios for critical minerals Note(s): ...
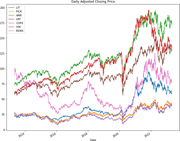
in Energy market and carbon emission spillovers in critical minerals investment: a dynamic connectedness approach
> Studies in Economics and Finance
Published: 21 September 2026
Figure 2. The daily adjusted closing price of portfolios for critical minerals Note(s): These prices are the raw data source from which the daily log-returns used in the model were derived. seven critical mineral portfolios from May 1 2013, to May 2 2023, with three V shapes A line graph com... More about this image found in The daily adjusted closing price of portfolios for critical minerals Note...
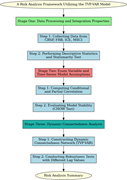
in Energy market and carbon emission spillovers in critical minerals investment: a dynamic connectedness approach
> Studies in Economics and Finance
Published: 21 September 2026
Figure 3. Analytics modules and workflow in the framework Note(s): Framed boxes are modules, and bulletin points are inputs, outputs or methods A flow diagram presents a three-stage risk analysis framework using the T V P V A R model, from data processing to a risk analysis summary. The art... More about this image found in Analytics modules and workflow in the framework Note(s): Framed boxes ar...
in Energy market and carbon emission spillovers in critical minerals investment: a dynamic connectedness approach
> Studies in Economics and Finance
Published: 21 September 2026
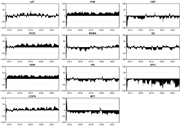
Figure 5. Net volatility spillover plot of the TVP-VAR model Note(s): Shades in the positive value range indicate the giving end of net volatility transmissions and vice versa A set of 11 time-series plots presents fluctuations for L I T, I Y M, C E F, P I C K, R E M X, G I I, V A W, V I X, ... More about this image found in Net volatility spillover plot of the TVP-VAR model Note(s): Shades in th...
in Energy market and carbon emission spillovers in critical minerals investment: a dynamic connectedness approach
> Studies in Economics and Finance
Published: 21 September 2026
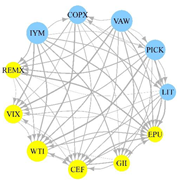
Figure 4. NPDC plot of the TVP-VAR connectedness analysis Note(s): The nodes in blue are net givers, and the nodes in yellow are net receivers of an uncertainty shock. The bold line indicates a higher spillover level than fine lines between variables over time A network diagram connects C ... More about this image found in NPDC plot of the TVP-VAR connectedness analysis Note(s): The nodes in b...
in Energy market and carbon emission spillovers in critical minerals investment: a dynamic connectedness approach
> Studies in Economics and Finance
Published: 21 September 2026
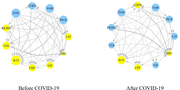
Figure 6. NPDC measure plots of TVP-VAR before and after COVID-19 Two network diagrams compare directed connections among 11 financial and risk variables before and after COVID-19. The article presents directed networks before COVID-19 and after COVID-19. Both networks contain C O P X, V A W... More about this image found in NPDC measure plots of TVP-VAR before and after COVID-19 Two network dia...
Journal Articles
Journal:
Studies in Economics and Finance
Studies in Economics and Finance 1–34.
Published: 15 September 2026
Published: 15 September 2026
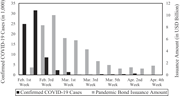
Figure 1. Confirmed COVID-19 cases and pandemic bond issuances by week Note(s): This figure presents the weekly evolutions of the number of newly confirmed COVID-19 cases and the issuance amount of corporate pandemic bonds in mainland China A dual-axis bar chart compares confirmed C O V I D ... More about this image found in Confirmed COVID-19 cases and pandemic bond issuances by week Note(s): Th...
Published: 15 September 2026
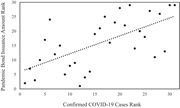
Figure 2. Confirmed COVID-19 cases and pandemic bond issuances by province Note(s): This figure depicts the relationship between confirmed COVID-19 cases and pandemic bond issuances by province in mainland China. The horizontal axis represents the rank of each province based on its number of co... More about this image found in Confirmed COVID-19 cases and pandemic bond issuances by province Note(s):...
Published: 15 September 2026
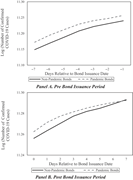
Figure 3. Confirmed COVID-19 cases around (non-)pandemic bond issuances Note(s): This figure presents the evolution of confirmed COVID-19 cases in mainland China during the 15 days (i.e. days [−7, + 7]) surrounding the issuances of pandemic bonds and their matched non-pandemic bonds. Panels A a... More about this image found in Confirmed COVID-19 cases around (non-)pandemic bond issuances Note(s): T...
Journal Articles
Journal:
Studies in Economics and Finance
Studies in Economics and Finance 1–20.
Published: 14 September 2026
in Shifting correlations: how trade policy uncertainty alters stock-T-bill relationships
> Studies in Economics and Finance
Published: 14 September 2026
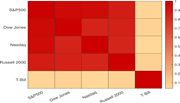
Figure 1. Heatmap representing the sample correlations of the de-GARCHed returns as defined in equation (3 ). Darker colors indicate stronger positive correlations, while lighter colors indicate weaker or negative correlations A 5-by-5 correlation heat map compares S and P 500, Dow Jones, Nasd... More about this image found in Heatmap representing the sample correlations of the de-GARCHed returns as d...
in Shifting correlations: how trade policy uncertainty alters stock-T-bill relationships
> Studies in Economics and Finance
Published: 14 September 2026
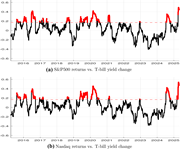
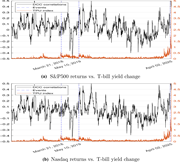
Figure 2. 60-day rolling correlation between stock returns and T-bill yield changes (black line), with periods exceeding one standard deviation highlighted in red. The dashed red line represents the threshold of one standard deviation Two time-series plots compare S and P 500 and Nasdaq returns... More about this image found in 60-day rolling correlation between stock returns and T-bill yield changes (...
in Shifting correlations: how trade policy uncertainty alters stock-T-bill relationships
> Studies in Economics and Finance
Published: 14 September 2026
Figure 3. Conditional correlations from the DCC model (black line, left axis), Trade Policy Uncertainty ( TPU ) index (red line, right axis), and key trade-related events (vertical blue-dashed lines) Two time-series plots compare D C C correlations and the T P U index, with event markers at M... More about this image found in Conditional correlations from the DCC model (black line, left axis), Trad...
in Shifting correlations: how trade policy uncertainty alters stock-T-bill relationships
> Studies in Economics and Finance
Published: 14 September 2026
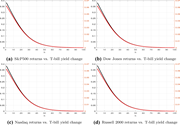
Figure 4. Impulse response function ( IRF ) of the stock–T-bill correlation to a one-standard-deviation shock in trade policy uncertainty (black line, left axis) and VIX (red line, right axis), expressed in percentage points Four plots compare S and P 500, Dow Jones, Nasdaq, and Russell 2000 ... More about this image found in Impulse response function ( IRF ) of the stock–T-bill correlation to a one-...
in Shifting correlations: how trade policy uncertainty alters stock-T-bill relationships
> Studies in Economics and Finance
Published: 14 September 2026
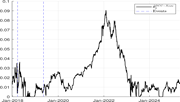
Figure 5. θ ^ 3 rolling window estimated coefficient (black line) from the D C C − X T P U model and break dates (dashed blue line, details in the text) A time-series plot rises sharply from 2021 to a peak near 0.09 in early 2022, then falls and remains most... More about this image found in θ ^ 3 rolling window estimated coefficient (black line) from the ...

