


This study aims to examine Sub-Saharan Africa (SSA), a region characterized by recurring violence that affects economic activity and macroeconomic stability.
Using a Dynamic Spatial Durbin Model with fixed effects estimated via the generalized spatial two-stage least squares estimator, this paper examines both the direct and indirect effects of conflicts on national and regional inflation over the period 1997–2022.
Regardless of the type of conflict, countries affected by armed violence, as well as their neighbors, experience inflationary pressures. This inflationary dynamic becomes self-sustaining over time and space in a relatively stable socioeconomic environment.
The study recommends that Sub-Saharan African countries enhance regional security cooperation to mitigate the negative effects of conflicts on price stability.
The methodological rigor allowed us to prove that spatial transmission of inflation is influenced by factors such as the road distance between a country's capital and the neighboring port, highlighting regional economic interconnections that amplify inflation. Monetary and real factors, as well as security issues, significantly contribute to inflationary pressure in the region.
1. Introduction
Sub-Saharan Africa (SSA) remains one of the most unstable regions in the world. Indeed, approximately 30% of the countries in this region were affected by armed conflicts in 2019 (Fang et al., 2020). Furthermore, Data from the Armed Conflict Location and Event Data (ACLED) for 2010 and 2022 highlight a significant increase in conflict indicators, underscoring the intensification of violence in the region.
In 2010, the average number of political violence events was relatively low at 33.91. However, this figure increased nearly tenfold to 306.33 in 2022, reflecting worsening political conflicts and armed confrontations. Similarly, violent protests and movements saw a sharp rise from an average of 10.67 in 2010 to 145.73 in 2022, indicating that growing social and political tensions were accompanied by escalating demonstrations. The average number of civilians killed through targeted violence also increased dramatically, from 29.15 in 2010 to 296.33 in 2022, highlighting the deterioration of security conditions and intensified human rights violations. Furthermore, reported deaths from violent events rose significantly, from 135.45 in 2010 to 710.33 in 2022, further illustrating the increasing human toll of these conflicts. These persistent conflicts disrupt intraregional trade, which is critical for land-based economies, leading to inflationary pressures and heightened economic instability (Nkemgha et al., 2023).
Recent economic data further illustrate a strong inflationary trend in the region. For example, inflation in Sub-Saharan Africa increased from 4.03% in 2010 to 9.39% in 2022, which is well above the global average. This trend contrasts with the modest growth in intra-African trade and the decline in the region's economic growth rate, which fell from 5.93% in 2010 to 3.56% in 2022 (World Bank, 2023). Despite these developments, the literature on the causes of inflation in Sub-Saharan Africa often overlooks the specific impact of armed conflicts, focusing more on traditional monetary or nonmonetary determinants.
This paper addresses this gap by analyzing, for the first time, the spillover effects of armed conflicts on inflation in the region, considering both the direct impacts on conflict-affected countries and the indirect effects on neighboring countries. This study is innovative in two key ways. First, it contributes to the literature on inflation determinants in Sub-Saharan Africa by identifying armed conflict as a critical factor influencing inflation levels within the region. Second, the paper employs a spatial econometric model to analyze these spillover effects, enabling the examination of both direct and indirect impacts of conflicts on inflation in neighboring countries (Elhorst, 2010; Elhorst and Vega, 2014). This methodology provides a more nuanced understanding of the complex dynamics at play, offering valuable insights for economic policy in the region.
Thus, this paper fills a significant gap in the analysis of inflation drivers in Sub-Saharan Africa and proposes an innovative approach to understanding the effects of armed conflicts on price stability. The remainder of this paper is organized as follows: the second section reviews the literature on the economic impacts of armed conflicts, with a particular emphasis on the relationship between conflicts and inflation. The third section details the methodology and the data used in this study, followed by an overview of the descriptive statistics. The next section presents the estimation results and discussion. Finally, the fifth section provides the conclusions of the study.
2. Literature review
Inflation is a complex and multifaceted economic phenomenon that can be influenced by a variety of factors. This literature review explores the determinants of inflation in Sub-Saharan Africa, focusing on traditional economic theories as well as more recent contributions that incorporate the role of insecurity and armed conflicts.
2.1 Theoretical framework
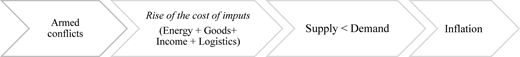
The theoretical literature on inflation distinguishes three main sources of inflation: demand-pull inflation, cost-push inflation, and monetary inflation. Demand‒pull inflation, rooted in Keynesian economics, occurs when aggregate demand exceeds aggregate supply, leading to a general rise in prices. Indeed, armed conflicts lead to an increase in overall demand, particularly from governments, households and enterprises. Conflicts cause a sharp rise in government spending on the military, logistics and rebuilding efforts, requiring the mobilization of significant financial resources and thus increasing the budget deficit (Tian et al., 2023). Armed conflicts also exacerbate markets for goods and services, resulting in increased demand for primary goods from households and businesses (Salvi et al., 2025). However, this increase in aggregate demand was met with limited aggregate supply due to declines in agricultural and industrial production and trade. Consequently, the imbalance between aggregate demand and supply exacerbates inflation.

In addition, cost-push inflation is triggered by rising production costs and shortages of energy and raw materials (Jain et al., 2022). Armed conflicts can destroy infrastructure and disrupt supply chains (Negi, 2026). Companies then find it difficult to access these supply chains, increasing production costs. To maintain their margins, these companies will therefore increase the prices of their products. Furthermore, armed conflicts cause an increase in energy prices (oil and gas) and the cost of raw materials as a whole (Al-Shwaf and Bell, 2025). Consequently, companies pass these price increases on to the wider economy, leading to inflation. Thus, conflicts reduce the overall supply, even when demand remains stable. This imbalance between supply and demand leads to cost-push inflation.
Monetary inflation is based on the quantity theory of money, which posits that inflation is a direct result of excessive growth in the money supply relative to the growth of goods and services. An expansion of the money supply leads to a rise in the general price level, especially when it does not match a corresponding increase in output (Mankiw, 1998). For monetarists and new classical economists, inflation arises when the money supply grows faster than the economy's output. They emphasize the role of expectations in the inflationary process. Indeed, to finance their deficit, governments can print money. This situation leads to a growing money supply and therefore inflation. In addition, armed conflicts increase government expenses and lead to this budget deficit. According to the new classical view, incorrect expectations about future inflation can lead to persistent inflation. Economists such as Friedman (1956), Brunner and Meltzer (1977), and Beitone et al. (2012) argue that inflation is fundamentally driven by excessive monetary expansion. In addition, external factors can drive inflation. Imported inflation occurs when external economic conditions, such as rising global prices for raw materials or a depreciation of the national currency, lead to higher domestic prices. Bezbakh (2011) discusses how shocks in one country, such as a rise in the price of imported goods, can lead to inflation in neighboring countries through trade links. Similarly, currency devaluation makes imports more expensive, directly affecting domestic prices and leading to inflationary pressures on both businesses and households.
2.2 Empirical evidence
In addition to traditional economic factors, there is growing recognition of the role of insecurity and armed conflicts in driving inflation. Siry and Traoré (2023) argue that insecurity, particularly stemming from humanitarian crises, can contribute to inflation. Armed conflicts often damage infrastructure, reduce agricultural production, and complicate logistics, which leads to supply shortages and price increases. These effects are particularly pronounced in Sub-Saharan Africa, where insecurity can have widespread implications for the economy. For example, disruptions in agricultural production and trade networks during conflict periods can drive up food prices, contributing to inflation. Additionally, some monetary policies adopted by governments in response to conflict, such as quantitative easing or accommodative monetary policies, can exacerbate inflationary pressures. The Central Bank of West African States (BCEAO, 2020) and the Organization for Economic Cooperation and Development (OECD, 2020) note that monetary expansion in response to economic instability can further fuel inflation.
Empirical studies have shown that the sources of inflation in Africa are diverse and often linked to both internal and external factors. Loungani and Swagel (2001), examining data from 1964–1998, reported that inflation inertia (the persistence of past inflation rates) plays a significant role in the inflationary process in many African countries. This phenomenon is particularly evident in countries with a history of high inflation, where expectations of future inflation are shaped by past experiences, creating a self-fulfilling cycle of inflation. Moreover, several studies have empirically explored the relationship between insecurity and inflation. Nkemgha et al. (2023) used the generalized method of moments (GMM) approach to analyze a panel of Central African countries between 2011 and 2017 and reported that insecurity was a key driver of inflation in the region. Their analysis suggests that rising insecurity, whether from armed conflicts or political instability, leads to higher inflation, particularly in economies already grappling with structural weaknesses. Thus, Nwosu et al. (2024) employed Granger causality tests to investigate the relationship between insecurity and inflation in Nigeria. Their findings revealed that insecurity drives inflation, whereas inflation does not seem to contribute to insecurity. This conclusion reinforces the perspective that conflicts and instability can lead to inflationary pressures, but inflation alone is unlikely to incite insecurity. This interactive effect of inflation or armed conflict via good governance or natural resources extends to the attractiveness of FDI in African countries south of the Sahara over the period 1996–2014 through the use of the GMM technique (Bobbo, 2018; Ezeoha and Ugwu, 2015).
Conversely, other studies have explored how inflation itself can fuel social unrest. For instance, Smith (2014) demonstrated that sudden and sharp increases in food prices in urban Africa were strongly correlated with civil unrest and protests. This underscores the importance of inflation not only as an economic issue but also as a catalyst for political instability. In addition, external factors, such as global oil prices and international trade relationships, significantly affect inflation in Sub-Saharan Africa. Guy and Kouadio (2018) reported that oil price increases have a long-term inflationary effect on the West African Economic and Monetary Union (WAEMU), although the effect is not immediate. Similarly, studies by Lim and Sek (2015) suggest that factors such as gross domestic product (GDP) growth, imports, and the money supply have a significant relationship with inflation, particularly in low-inflation economies. Nyanda (2021) focused on the Economic Community of Central African States (ECCAS) region and argued that inflation is strongly influenced by external trade relations, particularly fluctuations in global prices and exchange rates. He emphasized that policies aimed at mitigating imported inflation, particularly through managing exchange rate fluctuations and global price shocks, are crucial for stabilizing prices in the region. For these findings, armed conflicts disrupt economic activity, displace populations, damage infrastructure, and create uncertainty, all of which contribute to inflation.
In summary, this literature review underscores the importance of considering armed conflicts as direct and indirect drivers of inflation in SSA. Nevertheless, these existing studies present some limits: firstly the use of non-spatial methods to capture cross-border transmission of conflict-driven inflation; secondly these studies focus on single sub-regions rather than SSA as a whole; thirdly, they treat conflict as a single undifferentiated variable rather than disaggregating it into distinct types (political violence, protests, targeted killings, reported deaths). Therefore, this study contributes to the literature by taking account theses aspects and by focusing specifically on the spillover effects of conflicts on inflation in SSA.
3. Methodology and data
3.1 Specification of the econometric model
The literature commonly examines the determinants of inflation by focusing on monetary and real factors without excluding the factor of insecurity. It generally employs standard approaches such as the vector error correction method and the error correction model based on autoregressive distributed lag (ARDL) modeling. However, these models do not account for the cross-border effects of inflation, which is imported through neighboring countries. For this reason, we use the Dynamic Spatial Durbin Model (DSDM) with fixed effects (FEs) estimated via the generalized spatial two-stage least squares (GS2SLS) estimator to inspect the effect of armed conflicts on inflation in Sub-Saharan Africa. This model solves econometric problems such as endogeneity, multicollinearity, unobserved heterogeneity across countries, the dynamic persistence of inflation and disturbances omitted in trends and space that standard models cannot solve. [see Table A1 in appendix for all abbreviations and acronyms].
The dependent variable used to capture the level of inflation is the Consumer Price Index (CPI), as per Claus (1997) and Blix (1995). This index is the most commonly used index in the literature, as it reflects the general increase in prices. The CPI is determined by both monetary and non-monetary variables. The monetary approach considers that inflation is determined by the quantity of money relative to GDP and rational expectations (Azam, 2001). Inflation can also be imported through international trade, thus through trade openness and foreign direct investment (FDI). In fact, open economies are particularly vulnerable to external shocks, especially commodity prices, which can spill over to domestic prices and fuel inflation (Krugman and Wells, 2020; Yiheyis, 2013).
In addition to these theoretical determinants, we introduce variables that could play a role in explaining inflation within the context of SSA countries, drawing inspiration from recent literature. Among the plausible determinants, we include past inflation due to the sluggish adjustment of economic agents' expectations (Caceres et al., 2013; Woni and Ouedraogo, 2026). This lagged inflation variable highlights the persistence of price levels in SSA countries. In other words, inflation at any given time is strongly influenced by its previous level. Additionally, natural resources are controlled for in this model. We measure this by “total natural resources rents.” Indeed, when the profits from natural resources are not reinvested, they may fuel inflation (Nyanda, 2021).
Economic growth is also controlled for, as it influences inflation both in high-inflation and low-inflation countries (Lim and Sek, 2015). The level of economic activity is measured by the real GDP per capita growth rate, as used in Mantsie (2003). We also introduce credit to the economy, measured by net domestic credit. These credits may counteract inflation, as argued by Nyanda (2021). Owing to the increasing insecurity in SSA countries, we postulate that inflation is directly and indirectly determined by the level of armed conflict. We capture this variable with four indicators: the number of political violence events, the number of violent protest and demonstration events, the number of reported deaths, and the number of civilians killed by direct targeting. In fact, armed conflicts, particularly terrorism, are significantly predicted by inflation volatility and not inflation (Ajide and Alimi, 2023).
Based on the above theoretical discussion and drawing on the work of Nubukpo (2002) and Diop et al. (2008), Equation (1) presents the baseline dynamic specification used to examine the effects of conflict and selected macroeconomic factors on inflation:
Where α0 is the constant term, i and t denote the country and time, respectively, and the error term ε represents other factors that were observed to affect inflation in the SSA.
The linear model in Equation (1) can be estimated via ordinary least squares (OLS) regression if there is no spatial interdependence among countries. However, this assumption is not straightforward, as a country's inflation is determined not only by a combination of its own attributes but also by the influence of its geographical location on the inflation levels of other countries. Therefore, we extend this linear model by incorporating spatial lags to account for spatial interactions and the interplay between explanatory and dependent factors.
To identify spatial externalities, we extend the baseline model presented in Equation (1) by incorporating spatial dependence in both the dependent variable and the explanatory variables. Following the General Nesting Spatial Model (GNSM) proposed by Elhorst (2010) and Elhorst and Vega (2014), the extended specification is:
where Y is the dependent variable; X is the explanatory variable; W is the spatial weight matrix of NxN; γ, ρ and θ are the spatial autoregressive coefficients; η and β are the regression coefficients; the parameter α denotes specific time-dependent effects intended to control for omitted unit variables; and Wμ represents the interaction effects between the disturbance terms of the different units. These authors consider that a Spatial Durbin Model specification, derived from the restriction of the general model, is the most robust among the derived models. However, we conduct preliminary tests to guide the selection of our final model.
3.2 Spatial weighting matrix
This spatial lag, expressed through a spatial weight matrix W, allows the quantification of geographical, economic, cultural, and social proximity relationships among the countries studied. For the selection of the spatial weighting matrix W, the literature offers various types of weight matrices depending on the chosen neighborhood structure. Given the complexity involved in determining the proximity variable, we introduce eight weight matrices and use the Akaike Information Criterion (AIC) and Schwarz Bayesian information criterion (BIC) to select the one most suitable for our data. These matrices are constructed on the basis of the following basic hypothesis: the two countries are contiguous, the two countries share a common language, simple distance (most populated cities, kilometers (km)), simple distance between capitals (capitals, km), bilateral sea distance in kilometers, weighted distance (pop-wt, km) with theta = 1 (theta measures the sensitivity of trade flows to bilateral distance dkl), road distance between the capital of the first country and the relevant port in kilometers and road distance between the capital of the second country and the relevant port in kilometers. Table 1 shows the values of the AIC and BIC.
Akaike's information criterion and Bayesian information criterion
| Model | AIC | BIC |
|---|---|---|
| Matrice 1 | 8068.694 | 8182.805 |
| Matrice 2 | 8073.137 | 8187.247 |
| Matrice 3 | 8070.111 | 8184.222 |
| Matrice 4 | 8070.432 | 8184.543 |
| Matrice 5 | 8074.479 | 8188.589 |
| Matrice 6 | 8069.644 | 8183.755 |
| Matrice 7 | 8054.31 | 8168.42 |
| Matrice 8 | 8010.169 | 8124.28 |
The comparison of these information criteria across different specifications reveals that the AIC and BIC values are minimized for Matrix 8: the road distance between the capital of the second country and the relevant port in kilometers. Indeed, the spatial weighting matrix, which is based on road distances between capitals and major seaports, captures the specific structure of trade and price transmission (Limao and Venables, 2001; Mustra et al., 2013). Many countries in Sub-Saharan Africa are landlocked, and the majority of their imports are heavily dependent on the seaports of bordering countries. As a result, domestic prices and inflation dynamics are strongly influenced by transport costs along the main trade corridors connecting the capitals of landlocked countries to seaports. Thus, road distance to ports is a relevant indicator of economic interactions related to inflation transmission. Matrix 8 is, therefore, the most suitable and will be used in the model estimation.
3.3 Tests for Detecting global autocorrelation
In line with the literature, we use three statistics to detect global autocorrelation: the global Moran statistic (1948), Geary's statistic (1954), and the Getis and Ord statistic (Getis and Ord, 1992). The results of these tests reveal the existence of spatial dependence in inflation among Sub-Saharan African countries (see Table 2). Indeed, the significance of the various statistics confirms the presence of spatial autocorrelation. Thus, a country's inflation is likely influenced by the inflation levels of neighboring states. Inflation in these countries is spatially dependent. Ignoring spatial autocorrelation and using the OLS estimator leads to biased estimates. Table 2 shows the results of the spatial autocorrelation tests.
Detection of global autocorrelation
| Tests | Statistics |
|---|---|
| Moran's I | −0.006 (−17.271) *** |
| Geary's c | 1.005 (12.601) *** |
| Getis and Ord's G | 0.926 (−17.270) *** |
Note(s): ***p < 0.01, **p < 0.05, *p < 0.1
Figure 1 below illustrates Moran's diagram, indicating that inflation across Sub-Saharan African countries is negative. Therefore, there is spatial dispersion in the sample. This demonstrates that highly inflationary countries are generally geographically distributed around less inflationary countries, and vice versa.
 A scatter plot titled Moran's diagram of inflation. The plot features dozens of data points representing inflation values across Sub-Saharan African countries. The x-axis is labeled 'inflcp' and the y-axis is labeled 'Spatially lagged inflep'. Both axes display numerical values. The data points are scattered with a noticeable downward trend, indicating a negative correlation. A red regression line is present, sloping downwards from left to right. The plot includes a legend indicating that blue circles represent 'Winflcp' and a red line represents 'Fitted values'. The Moran's I value is -0.0059 and the P-value is 0.0010, suggesting spatial dispersion in the sample. Highly inflationary countries are geographically distributed around less inflationary countries, and vice versa. All values are approximated.
Moran's diagram of inflation. Source: Authors
A scatter plot titled Moran's diagram of inflation. The plot features dozens of data points representing inflation values across Sub-Saharan African countries. The x-axis is labeled 'inflcp' and the y-axis is labeled 'Spatially lagged inflep'. Both axes display numerical values. The data points are scattered with a noticeable downward trend, indicating a negative correlation. A red regression line is present, sloping downwards from left to right. The plot includes a legend indicating that blue circles represent 'Winflcp' and a red line represents 'Fitted values'. The Moran's I value is -0.0059 and the P-value is 0.0010, suggesting spatial dispersion in the sample. Highly inflationary countries are geographically distributed around less inflationary countries, and vice versa. All values are approximated.Moran's diagram of inflation. Source: Authors
The autocorrelation test highlights the presence of spatial autocorrelation, but it does not provide information about its nature. This underscores the need to investigate the appropriate spatial model.
3.4 Tests for spatial model specification
A spatial model can be specified in either a static or dynamic form (Yu et al., 2008; Ouedraogo and Ouedraogo, 2024). In this article, we choose the dynamic specification because our dependent variable is influenced by past inflation due to the slow adjustment of economic agents' expectations (Caceres et al., 2013). Additionally, we support this choice by conducting Lagrange multiplier (LM) tests, Breusch‒Pagan‒Godfrey tests, and tests by Baltagi and Sosa‒Escudero, following Anselin et al. (2008), to detect the presence of spatial and serial autocorrelation. Table 3 shows the results of these tests.
Local autocorrelation tests
| Tests | Statistics |
|---|---|
| Breusch‒Pagan LM Test -Two Side | 75.6952 *** |
| Breusch‒Pagan ALM Test -Two Side | 78.9371 |
| Sosa-Escudero-Yoon LM Test -One Side | 8.7003*** |
| Sosa-Escudero-Yoon ALM Test -One Side | 8.8847*** |
| Baltagi-Li LM Autocorrelation Test | 0.3505*** |
| Baltagi-Li ALM Autocorrelation Test | 3.5925*** |
| Baltagi-Li LM AR (1) Joint Test | 79.2876*** |
Note(s): ***p < 0.01, **p < 0.05, *p < 0.1
The results of the LM test and its robust version show that the various statistics for the dependent variable and error terms are statistically significant at the 1% level. Consequently, the hypothesis of omitting autocorrelation in the error terms and the endogenous variable is rejected. This confirms the presence of autocorrelation in the errors and the spatially lagged dependent variable. Furthermore, the Breusch‒Pagan‒Godfrey, Baltagi, and Wooldridge tests in the table confirm the existence of serial autocorrelation at the 1% level. This strengthens the idea that spatial autocorrelation is present in both the dependent variable and the exogenous variables. Thus, our spatial model must take into account serial autocorrelation by including dependent variables delayed in time and in space .
Equation (3) combines the baseline specification in Equation (1) with the spatial dynamic framework introduced in Equation (2) . It extends the baseline model by incorporating the temporal lag of inflation, its contemporaneous and time-lagged spatial components, and the spatial lags of the explanatory variables. The resulting empirical specification is written as follows:
With ; ; i = 1 … 33 and t = 1 … 26,
Where α and θ represent the coefficients for direct effects and spatial effects, respectively.
To estimate Equation (3), we use a DSDM with fixed effects (FEs), estimated via the generalized two-stage spatial least squares estimator (GS2SLS). The DSDM specification allows the model to capture both the spatial dependence of the dependent variable and the spatial spillover effects of the explanatory variables. The GS2SLS estimator allows us to address endogeneity issues. In addition, the inclusion of lagged dependent variables allows us to take into account the persistence of inflation over time, whereas FE controls for unobserved heterogeneity across countries. To this end, we use the lagged dependent variable and spatially lagged explanatory variables as endogenous instruments, in line with the approach proposed by Kelejian and Prucha (1998). Table 4 shows the definitions and sources of the variables, as well as their statistics (Pairwise correlations are shown in Table A2 in appendix).
Descriptive statistics
| Code variables | Definitions | mean | Sd | Min | Max | Data source |
|---|---|---|---|---|---|---|
| VIO_PO | Political Violence | 94.91 | 208.5 | 0 | 1,652 | ACLED |
| MOUV_PRO | Movement and violent Protest | 39.30 | 127.7 | 0 | 1,772 | ACLED |
| CIVIL_CIBLAGE | Civilians killed by direct targeting | 147.7 | 580.7 | 0 | 9,337 | ACLED |
| DEC_SIGNALE | Death all reported | 514.3 | 3.280 | 0 | 73,811 | ACLED |
| M2 | Broad money (% of GDP | 26.85 | 13.41 | 0.035 | 1,515 | WDI |
| CRED | Domestic credit to private sector (% of GDP) | 18.81 | 21.34 | 0.0016 | 142.4 | WDI |
| FDI | Foreign direct investment. net inflows (% of GDP) | 3.170 | 4.807 | −17.29 | 46.28 | WDI |
| GDPG | GDP growth (annual % | 3.997 | 4.606 | −28.10 | 33.63 | WDI |
| INFLCP | Inflation. Consumer prices (annual %) | 7.843 | 10.83 | −16.86 | 104.7 | WDI |
| TNRES | Total natural resources rents (% of GDP) | 10.96 | 10.36 | 0.256 | 59.68 | WDI |
| TRADE | Trade (% of GDP) | 63.37 | 28.51 | 2.699 | 175.8 | WDI |
| POSTAB | Political Stability and Absence of Violence Terrorism | −0.557 | 0.810 | −2.665 | 1.201 | WDI |
4. Results and discussion
4.1 Results of the baseline model
The results of the baseline model are presented in Table 5. They show that the error variance, measured by sigma squared, is significant at the 1% level for all regressions, indicating that the independent variables significantly influence the dependent variable. Although the sigma squared variance indicates a dispersion of errors in the model, the quality of this dispersion is captured by the significance of the spatial rho. Furthermore, the spatial autocorrelation parameter, Rho-spatial, with values of 1.102, 1.171, 1.192 and 1.128 for the different equations, is positive and significant at the 1% level, suggesting the existence of a spatial diffusion effect. In other words, inflation in a SSA country increases in proportion to inflation in neighboring countries. Specifically, if inflation in all neighboring countries increases by 1 unit, inflation in the country in question increases by 1.102, 1.171, 1.192 and 1.128 units, depending on the nature of the conflicts in the neighboring country. These results corroborate findings from other regions, such as Asia, confirming that their economies are exposed to significant inflationary spillovers from China (Osorio and Unsal, 2013).
Estimation results of the main model
| Variables | Direct effects | Indirect effects | Direct effects | Indirect effects | Direct effects | Indirect effects | Direct effects | Indirect effects |
|---|---|---|---|---|---|---|---|---|
| Lagged inflation | 0.574*** | 0.566*** | 0.569*** | 0.550*** | ||||
| (0.0278) | (0.0285) | (0.0275) | (0.0275) | |||||
| Lagged inflation of neighboring countries | 0.419*** | 0.324*** | 0.451*** | 0.307*** | ||||
| (0.118) | (0.103) | (0.107) | (0.100) | |||||
| Political violence | 0.00874 | 0.0436 | ||||||
| (0.00606) | (0.0287) | |||||||
| Movement and violent Protest | 0.0385*** | 0.00185 | ||||||
| (0.00888) | (0.0328) | |||||||
| Civilians killed by direct targeting | 0.00558*** | −0.0105 | ||||||
| (0.00186) | (0.00771) | |||||||
| Death all reported | 0.00170*** | 0.000829 | ||||||
| (0.000307) | (0.00135) | |||||||
| Broad money | −0.391** | 2.829*** | −0.475*** | 3.060*** | −0.332** | 3.005*** | −0.305* | 3.501*** |
| (0.159) | (0.798) | (0.160) | (0.770) | (0.158) | (0.776) | (0.157) | (0.788) | |
| GDP growth | −0.819*** | −3.305*** | −0.795*** | −3.963*** | −0.817*** | −4.130*** | −0.789*** | −3.494*** |
| (0.220) | (0.930) | (0.218) | (0.868) | (0.218) | (0.937) | (0.216) | (0.880) | |
| Total natural resources rents | 0.725*** | −0.179 | 0.699*** | 0.190 | 0.743*** | 0.116 | 0.716*** | 0.639 |
| (0.197) | (0.789) | (0.196) | (0.753) | (0.196) | (0.760) | (0.194) | (0.788) | |
| Domestic credit to private sector | −0.431* | −4.674*** | −0.176 | −4.864*** | −0.460** | −4.668*** | −0.460** | −4.456*** |
| (0.227) | (1.475) | (0.232) | (1.464) | (0.226) | (1.466) | (0.223) | (1.453) | |
| Political stability | −2.678 | −32.21 | −4.193* | −46.20** | −3.040 | −63.22*** | −2.053 | −42.00* |
| (2.395) | (24.24) | (2.157) | (21.07) | (2.253) | (23.10) | (2.203) | (23.49) | |
| Trade | −0.103 | −0.138 | −0.106* | −0.274 | −0.113* | −0.219 | −0.118* | −0.563 |
| (0.0628) | (0.442) | (0.0620) | (0.423) | (0.0623) | (0.441) | (0.0618) | (0.444) | |
| Foreign direct investment | 0.758*** | −8.840*** | 0.762*** | −8.482*** | 0.628*** | −8.611*** | 0.424* | −8.343*** |
| (0.213) | (1.472) | (0.211) | (1.482) | (0.215) | (1.481) | (0.218) | (1.477) | |
| Spatial rho | 1.102*** | 1.171*** | 1.192*** | 1.128*** | ||||
| (0.172) | (0.167) | (0.172) | (0.166) | |||||
| Variance sigma2 | 670.8*** | 657.4*** | 662.2*** | 649.2*** | ||||
| (32.00) | (31.36) | (31.62) | (30.96) | |||||
| Observations | 825 | 825 | 825 | 825 | 825 | 825 | 825 | 825 |
| R-squared | 0.052 | 0.052 | 0.076 | 0.076 | 0.054 | 0.054 | 0.073 | 0.073 |
| Number of countries country | 33 | 33 | 33 | 33 | 33 | 33 | 33 | 33 |
Note(s): Standard errors in parentheses ***p < 0.01, **p < 0.05, *p < 0.1
This phenomenon can be explained by trade exchanges between SSA countries, which create a price transmission effect. Thus, an increase in inflation in a neighboring country, due to rising import prices, affects the domestic inflation of the country concerned. This is particularly due to the economic and trade interdependence between countries in the region, where the prices of imported goods are influenced by the economic and inflationary conditions of neighboring countries.
Therefore, the hypothesis of spatial dependence between inflation levels in the sample countries cannot be rejected. Indeed, inflation in an SSA country depends not only on its own economic characteristics but also on the inflation levels of neighboring countries through geographic factors such as the road distance between their capitals and their respective ports. This geographical and commercial interconnection strengthens the impact of transnational economic shocks.
The estimation via the DSDM-GS2SLS approach confirms the existence of a significant spatial diffusion effect of inflation between African countries. Specifically, an increase in inflation in neighboring countries in previous years tends to increase the level of inflation in the country concerned, depending on the nature of the conflicts in those neighboring countries. This demonstrates that inflation in neighboring countries is not just a one-time phenomenon: it has lasting effects on domestic inflation through a mechanism of spatio-temporal expectations by economic agents. The expectations of economic factors in countries affected by conflicts are influenced by past economic development in neighboring countries, thus creating an environment conducive to the spread of inflationary pressures, confirming the importance of regional economic interactions.
The results of the base model confirm the importance of spillover effects of armed conflicts on inflation in Sub-Saharan African countries. These effects are amplified by spatial dependencies between neighboring countries, which share important commercial and geographical ties, and by the way inflation expectations are formed at the regional level. These results further confirm the cross-border effects of conflicts on inflation, as found in previous investigations (De Groot et al., 2011; Falk and McGinnis, 2016).
The results indicate that delayed inflation in the countries considered has a significant direct effect on current inflation in those same countries, with coefficients varying slightly depending on the introduction of the conflict variable. A 1-unit increase in inflation in the previous period leads to an increase of between 0.550 and 0.574 units in inflation in the current period, depending on the type of conflict. This suggests that current inflation is strongly influenced by past inflation in countries affected by conflict. These results confirm the autoregressive dynamics of inflation persistence, as advanced by classical theory (Friedman, 1956; Brunner and Meltzer, 1977; Beitone et al., 2012).
The results show that armed conflicts, such as the number of political violence events, the number of violent protests and demonstrations, the number of reported deaths, and the number of civilians killed by direct targeting, contribute to inflation in Sub-Saharan African countries. Specifically, a unit increase in these various types of conflict leads to increase in inflation of 0.00874, 0.0385, 0.00558 and 0.0017 units, respectively. Thus, conflicts fuel inflation through their negative effects on aggregate supply. Indeed, national and regional supply chains can be disrupted by conflicts, leading to shortages of food and other essential goods. Regardless of the type of armed conflict, they contribute to increasing inflation in the crisis-affected country as well as in neighboring countries, thus confirming the hypothesis of imported inflation. Thus, inflation has become a contagious phenomenon in Africa, as it spreads through neighboring countries.
These results confirm the empirical findings of Mbuagbaw et al. (2011) and Brück et al. (2014), who found a clear link between conflicts and rising inflation, particularly in post conflict periods. However, unlike their studies, which use conventional methods that are unable to correct for spatial autocorrelation bias and ignore the diversity of conflicts, their cross-border effects, and the memory effects of past conflicts over time and space, the weakness of their results can be explained. By taking these factors into account, we strengthen the credibility and originality of our results. Furthermore, the application of the DSDM-GS2SLS estimation technique is better suited to analyzing spatial and temporal data, particularly in the inflationary African context, where armed conflicts spread geographically over time and space.
Security measures taken by neighboring countries, which constitute a production cost for businesses, are passed on to consumers in the form of higher prices. This confirms the cost-push inflation effect. The spatial effect of conflicts on inflation in neighboring countries can also be explained by the instability of the labor market and a loss of productivity due to the displacement of labor caused by conflicts.
The money supply has positive and significant indirect effects on inflation, but the direct effects are negative. An increase in the money supply in neighboring countries exacerbates inflation in the country concerned. These results can be explained by the fact that Sub-Saharan African countries are highly interconnected and interdependent, such that a monetary shock generates cross-border effects on inflation in neighboring countries. The monetary policy of neighboring countries would thus have prompted the concerned country to adopt a similar policy, resulting in joint inflation.
Economic growth negatively influences inflation, both directly and indirectly, in Sub-Saharan African countries. This implies that inflation in a country can be reduced by increasing production in that country as well as in neighboring countries. These results can be explained by the low level of economic growth in SSA countries, which does not create enough pressure to drive prices up. The low growth level also does not compensate for the increase in imports from neighboring countries, thus contributing to reducing inflation in those countries. Additionally, population movements (labor force) can create an imbalance in the labor market, reduce production, and consequently lower inflation in crisis-affected countries. This low growth rate could also be due to restrictive monetary policies, which explain the observed decrease in inflation. Our results support the theory put forward by Ogbe et al. (2024) that the spatial effects of armed conflicts in Africa can transcend the continent's economic growth.
The natural resources present in a country positively affect inflation but do not impact the price levels of neighboring countries. These resources fuel conflicts when abundant in a nation, which worsens inflation in SSA countries. Indeed, the exploitation of natural resources generates revenue, increases purchasing power, and stimulates both domestic and external demand, leading to higher prices in the concerned country and contributing to increased inflation in neighboring countries, which compete for the same resources.
Credit to the private sector, political stability, and trade openness contribute to reducing inflation both directly and indirectly. Indeed, an increase in private sector credit, an improvement in political stability, and trade openness to external markets in a country lead to a reduction in inflation in that country as well as in neighboring countries. Bank credit promotes productive investment, which increases the supply of goods and services and leads to lower inflation, according to the law of supply. Political stability guarantees long-term investment, thus increasing supply and enabling governments to implement effective anti-inflationary policies. Opening African markets increases the availability of goods and services, which can also help reduce inflation in the region. International competition forces African companies to innovate and improve their efficiency, thereby reducing their production costs and, consequently, their prices.
Foreign direct investment increases national inflation but reduces inflation in neighboring countries. These results can be explained by the fact that FDI stimulates domestic demand, which increases inflation in the concerned country. Consequently, the increase in FDI can lead to the relocation of prices to neighboring countries, thereby reducing their inflation levels.
4.2 Robustness analysis
The baseline model was re-estimated via the same spatial weight matrix selected on the basis of the AIC and BIC information criteria. This re-estimation maintained the same parameters related to armed conflicts but replaced the inflation variable measured by the CPI with the GDP deflator. The GDP deflator is an inflation indicator that compares the nominal value of a country's gross domestic product to its real value and is generally considered a broader and more comprehensive measure of inflation, encompassing consumption, investment, and exports.
The results obtained from this model are similar to those of the baseline model (see Table 6), and they prove more robust in terms of statistical significance. This finding confirms the validity of our initial hypothesis, which posited that armed conflicts have a significant inflationary impact on SSA countries while also highlighting the contagious nature of inflation through the road distance between the capital of the second country and the relevant port in kilometers.
Robustness test results
| Variables | Direct effects | Indirect effects | Direct effects | Indirect effects | Direct effects | Indirect effects | Direct effects | Indirect effects |
|---|---|---|---|---|---|---|---|---|
| Lagged inflation | 0.448*** | 0.448*** | 0.449*** | 0.463*** | ||||
| (0.0317) | (0.0321) | (0.0314) | (0.0293) | |||||
| Lagged inflation of neighboring countries | −0.0979 | −0.0574 | −0.0245 | 0.0148 | ||||
| (0.110) | (0.109) | (0.104) | (0.1000) | |||||
| Political violence | 0.0237*** | 0.101*** | ||||||
| (0.00756) | (0.0324) | |||||||
| Movement and violent protest | 0.0288** | 0.0822** | ||||||
| (0.0113) | (0.0416) | |||||||
| Civilians killed by direct targeting | 0.0108*** | −0.0118 | ||||||
| (0.00232) | (0.00902) | |||||||
| Death all reported | 0.00389*** | 0.000916 | ||||||
| (0.000370) | (0.00169) | |||||||
| Broad money | −0.882*** | 1.618* | −0.933*** | 2.089** | −0.749*** | 2.452*** | −0.699*** | 3.043*** |
| (0.199) | (0.953) | (0.203) | (0.941) | (0.198) | (0.919) | (0.189) | (0.918) | |
| GDP growth | −0.680** | −1.228 | −0.701** | −1.943* | −0.661** | −1.641* | −0.611** | −1.386 |
| (0.276) | (0.981) | (0.278) | (0.996) | (0.274) | (0.997) | (0.261) | (0.929) | |
| Total natural resources rents | 1.203*** | −0.431 | 1.228*** | 0.346 | 1.283*** | 0.455 | 1.212*** | 1.115 |
| (0.248) | (1.012) | (0.249) | (0.990) | (0.247) | (0.981) | (0.235) | (0.965) | |
| Domestic credit to private sector | −0.410 | −4.800*** | −0.230 | −5.386*** | −0.440 | −4.872*** | −0.477* | −4.300** |
| (0.284) | (1.844) | (0.294) | (1.860) | (0.285) | (1.844) | (0.271) | (1.757) | |
| Political stability | −1.570 | −1.393 | −6.051** | −44.38* | −3.649 | −70.21** | −1.064 | −35.84 |
| (3.003) | (30.07) | (2.742) | (26.03) | (2.852) | (30.14) | (2.682) | (29.29) | |
| Trade | −0.147* | −0.444 | −0.172** | −0.817 | −0.184** | −0.901 | −0.183** | −1.234** |
| (0.0788) | (0.569) | (0.0789) | (0.556) | (0.0783) | (0.556) | (0.0747) | (0.543) | |
| Foreign direct investment | 1.528*** | −5.660*** | 1.655*** | −3.586** | 1.372*** | −3.790** | 0.819*** | −3.475** |
| (0.264) | (1.718) | (0.264) | (1.678) | (0.267) | (1.654) | (0.261) | (1.596) | |
| Spatial rho | 0.474*** | 0.439*** | 0.391*** | 0.410*** | ||||
| (0.125) | (0.125) | (0.122) | (0.124) | |||||
| Variance sigma2 | 1,055*** | 1,066*** | 1,050*** | 953.6*** | ||||
| (50.01) | (50.56) | (49.76) | (45.20) | |||||
| Observations | 825 | 825 | 825 | 825 | 825 | 825 | 825 | 825 |
| R-squared | 0.067 | 0.067 | 0.068 | 0.068 | 0.073 | 0.073 | 0.126 | 0.126 |
| Number of countries | 33 | 33 | 33 | 33 | 33 | 33 | 33 | 33 |
Note(s): Standard errors in parentheses ***p < 0.01, **p < 0.05, *p < 0.1
However, an interesting distinction emerges: the impact of conflicts in a country seems to be less pronounced on that country's inflation than on the inflation of neighboring countries. This result suggests that the inflation generated by conflicts is more strongly felt beyond the immediate borders of the crisis country, likely due to regional economic interconnectedness. The indirect effects of inflation, caused by factors such as trade disruptions, rising import prices, and decreased productivity, thus affect neighboring countries more markedly.
This phenomenon of spillover inflation being more intense than the direct effects of conflicts can be explained by mitigation actions implemented in the countries directly affected by the crisis. Indeed, these countries may adopt economic policies aimed at reducing the immediate impacts of conflicts, such as loosening monetary policies, importing essential goods to address shortages, or involving financial institutions to stabilize internal prices. These measures can reduce the direct impact of inflation in crisis countries, but these effects are often insufficient to prevent the spread of inflation to neighboring countries, which do not benefit from the same mitigation strategies.
5. Conclusion
The objective of this paper was to examine the spillover effects of armed conflicts on inflation in Sub-Saharan African countries. By applying a dynamic spatial Durbin model to data covering the period from 1997–2022, this study reveals several key findings. Indeed, the estimates show that armed conflicts in a SSA country not only increase inflation within the country but also contribute to inflation across the entire region. This inflationary effect spreads primarily through disruptions in supply chains, particularly for essential goods. The spatial transmission of inflation is influenced by factors such as the road distance between a country's capital and the neighboring port, highlighting regional economic interconnections that amplify inflation. Furthermore, the persistence of armed conflicts in Africa contributes to inflationary pressures through regional spillover mechanisms.
Monetary and real factors, as well as security issues, significantly contribute to inflationary pressure in the region. Controlling inflation in SSA countries requires a regional approach, taking into account both monetary policies and the broader macroeconomic environment. On the one hand, the coordination of interest rates among regional central banks, multilateral monitoring of monetary aggregates and sterilization mechanisms help to contain, in the short term, inflationary pressures imported from neighboring countries in crisis. On the other hand, structural and security interventions (securing trade corridors, building up regional strategic stocks and strengthening local productive capacities) tackle the spatial transmission mechanisms of inflation identified in this analysis. Effective anti-inflationary policy in SSA must integrate these two dimensions in a coordinated and participatory manner across countries.
The implementation of these policies requires the involvement of regional institutions such as ECCAS and Economic Community of West African States. These institutions could establish a regional observatory on prices and conflicts to monitor inflationary spillover effects and secure trade corridors. This would support the African continental free trade area. Finally, central banks should harmonize their monetary policy responses to cross-border inflationary shocks caused by conflicts. Otherwise, future research could focus on assessing other indicators of conflict, extending the analysis to other developing regions, or investigating the non-linear or threshold effects of conflict intensity on inflation.
Appendix
List of abbreviation and acronyms used in the paper
| Abbreviations and acronyms | Definitions |
|---|---|
| ACLED | Armed Conflict Location and Event Data |
| AIC | Akaike Information Criterion |
| ARDL | Autoregressive Distributed lag |
| BCEAO | Central Bank of West African States |
| BIC | Bayesian Information Criterion |
| CPI | Consumer Price Index |
| DSDM | Dynamic Spatial Durbin Model |
| ECCAS | Economic Community of Central African States |
| FDI | Foreign Direct Investment |
| FE | Fixed Effects |
| GDP | Gross Domestic Product |
| GMM | Generalized Method of Moments |
| GNSM | General Nesting Spatial Model |
| GS2SLS | Generalized Spatial Two-stage Least Squares |
| Km | Kilometers |
| LM | Lagrange multiplier |
| OECD | Organization for Economic Cooperation and Development |
| OLS | Ordinary Least Squares |
| SSA | Sub-Saharan Africa |
| WAEMU | West African Economic and Monetary Union |
Pairwise correlations
| Variables | (INFLCP) | (VIO_PO) | (MOUV_PRO) | (CIVIL_CIBLAGE) | (DEC_SIGNALE) | (M2) | (GDPG) | (TNRES) | (CRED) | (POSTAB) | (TRADE) | (FDI) |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| INFLCP | 1.000 | |||||||||||
| VIO_PO | 0.180*** | 1.000 | ||||||||||
| MOUV_PRO | 0.177*** | 0.337*** | 1.000 | |||||||||
| CIVIL_CIBLAGE | 0.292*** | 0.520*** | 0.070** | 1.000 | ||||||||
| DEC_SIGNALE | 0.315*** | 0.374*** | 0.019 | 0.797*** | 1.000 | |||||||
| M2 | −0.071** | −0.003 | 0.242*** | −0.137*** | −0.068** | 1.000 | ||||||
| GDPG | −0.087** | −0.117*** | −0.097*** | −0.006 | −0.001 | −0.207** | 1.000 | |||||
| TNRES | 0.138*** | 0.000 | −0.087** | 0.108*** | 0.128*** | −0.186** | 0.014 | 1.000 | ||||
| CRED | −0.051 | 0.051 | 0.370*** | −0.021 | −0.014 | 0.705*** | −0.094** | −0.199** | 1.000 | |||
| POSTAB | −0.186*** | −0.521*** | −0.127*** | −0.385*** | −0.251*** | 0.259*** | 0.026 | −0.242** | 0.199*** | 1.000 | ||
| TRADE | −0.017 | −0.274*** | −0.147*** | −0.116*** | −0.021 | 0.172*** | −0.042 | 0.280*** | 0.079** | 0.318*** | 1.000 | |
| FDI | 0.113*** | −0.026 | −0.040 | 0.143*** | 0.256*** | −0.066* | 0.105*** | 0.129*** | −0.058* | 0.017 | 0.226*** | 1.000 |
Note(s): ***p < 0.01, **p < 0.05, *p < 0.1

