This study aims to help nonprofit organizations (NPOs) implement business excellence models (BEMs). The authors identify and rank critical success factors and barriers to implementing BEMs among NPOs in Saudi Arabia and investigate the impact of human resources availability on BEM implementation in these organizations.
Based on the review of relevant literature, the authors designed a questionnaire completed by 138 NPOs. Factor analysis was used to measure and rank the criticality of success factors and barriers to BEM implementation. A Kruskal–Wallis nonparametric test was conducted to compare answers across groups classified by the number of full-time employees in the organization.
The study identifies the five most critical success factors for implementing BEMs in Saudi NPOs: data analysis and reporting capabilities, effective organizational communication, implementation strategy and approach, use of benchmarking and adoption of a clear governance framework. The five most critical barriers to implementing BEMs are the lack of a culture of continuous improvement, organizational strategy, qualified employees, customer orientation and clear organizational roles and responsibilities. The number of full-time employees in Saudi NPOs does not significantly impact the success or failure of implementing BEMs.
This paper is a continuation of research that aims to increase BEM adoption among NPOs, including micro-NPOs, in Saudi Arabia and, by extension, other countries.
Introduction
Organizations today are continuously searching for practical approaches to enhance their management capabilities and achieve desired business results. One of these approaches that appeal to many organizations is business excellence models (BEMs) (Dahlgaard et al., 2013).
BEMs gained popularity after the introduction of the Baldridge National Quality Award in the USA in the 1980s and the European Foundation for Quality Management (EFQM) Quality Award in Europe in the 1990s (Mann et al., 2011). However, successfully implementing a BEM depends on many factors, including management’s commitment and leadership, the organization’s size, sector, human resource engagement, organizational structure and culture, and the availability of needed infrastructure and resources (Dahlgaard et al., 2013).
Over the past decade, nonprofit organizations (NPOs) have become increasingly crucial in driving social and welfare development and are now essential to societies in virtually every country worldwide (Hudson, 2005; Weerawardena et al., 2010). Given this, NPOs are becoming a key area of focus for governments and policymakers. The interest in implementing BEMs in NPOs is increasingly driven by pressures from governments, donor organizations and society in general (Claeye and Jackson, 2012). Al-Tabbaa et al. (2013) indicate that modified versions of original BEMs are applicable within the nonprofit sector. However, NPOs face difficulties implementing BEMs due to their limited financial management practices, inadequate fundraising abilities, ineffective governance and limited human resources (Minzner et al., 2013).
Micro-, small- and medium-sized enterprises (MSMEs) are the driving force of economic growth in most countries (Drbie and Kassahun, 2013). They represent more than 85% of total business establishments, contribute more than 50% of gross domestic product and use over 65% of the entire workforce (Alasrag, 2006). Like NPOs, MSMEs face significant difficulties when implementing BEMs given their limited access to external financing, markets, technology resources, advisory training and services, skilled human resources, infrastructure and other key inputs (Drbie and Kassahun, 2013).
Saudi Arabia has more than 1,600 registered NPOs, and the number is growing rapidly, given more relaxed regulations introduced in 2015 (Source: Ministry of Human Resources and Social Development). According to a 2013 study by the International Centre for Research and Studies (Medad Centre, 2014), NPOs in Saudi Arabia are typically challenged by the following:
most employees in Saudi NPOs are not specialized in their fields or functions;
few training programs are directed at developing employees in NPOs;
many NPOs have limited financial resources and financial management capabilities;
lack of governance structures; and
limited knowledge of or experience in strategic planning and strategy implementation.
The goal of this study is focused on identifying and ranking critical success factors and barriers affecting BEM implementation in NPOs in Saudi Arabia. The study also investigates the impact of the availability of human resources, measured in terms of full-time employees on the identified success factors and barriers. This will help develop policies, practices and models to increase the BEMs adoption rate and successful implementation among Saudi Arabia’s micro-NPOs. Furthermore, MSMEs and NPOs in other countries can benefit from the findings and conclusions of this study.
We note that the scope of this research is limited by defining micro-organizations in terms of full-time employees. While this definition is widely used in defining organizational size, other definitions include financial measures such as capital or annual revenue are used in different countries to define MSMEs (Cunningham and Rowley, 2008). In addition, while having limited resources, including human resources, has been identified in the literature as one of the main characteristics of micro-NPOs and SMEs, the impact of having a small number of employees may have been mitigated in recent years with advances in communication and information technology (Josefy et al., 2015).
Literature review
Business excellence models background, benefits and limitations
BEMs can be defined as frameworks that help organizations achieve excellence (Medhurst and Richards, 2003). Unlike TQM, they provide clear methodologies for achieving BE, contributing to their popularity worldwide (Gómez et al., 2011). BEMs provide an efficient way to achieve business excellence in terms of both financial and nonfinancial results (Bou-Llusar et al., 2009; Saunders and Wilson, 2001; Talwar, 2010; Boulter et al., 2013).
According to Talwar (2010), many organizations implementing BEMs reported improvements in their processes and customer satisfaction. Furthermore, many studies conducted on winners of NQAs based on BEMs show that better market shares, increased sales and profit, enhanced employee satisfaction and a boost in overall competitiveness have been reported by these winners (Lakhe and Mohanty, 1994; Hendricks and Singhal, 1997). Boulter et al. (2013) compared the performance of 85 NQA winners in 35 European countries over 11 years. Their study reveals that winning organizations achieve significantly better results than those without awards.
However, there has been increasing debate in recent years about the value of BEMs (Doeleman et al., 2014). While award-winning organizations have achieved better financial results, they have not achieved top results in their industries (Talwar, 2010). In a study conducted by NIST, 17 publicly traded MBNQA recipients underperformed the S&P 500. They reported an 18.5% return compared to a 33.58% return for the S&P 500. SAI Global developed a similar index to track the performance of Australian Business Excellence Award winners. However, indices designed to track the winning organizations’ performance were discontinued because NIST and SAI Global felt that financial performance is not necessarily correlated to BEMs implementation and award winning (Talwar, 2010).
In summary, some of the limitations of BEMs relevant to this research include the following:
the long time required to see results (Doeleman et al., 2014);
inconsistency of results achieved across various countries (Al-Tabbaa et al., 2013; Talwar, 2011);
inconsistency of results achieved across business sectors (Talwar, 2010);
difficulties implementing BEMs in the nonprofit sector (Eskildsen et al., 2004);
inconsistencies among various BEMs around the world (Talwar, 2011);
lack of standard implementation methodology (Campatelli et al., 2011; Wongrassamee et al., 2003);
the high cost of implementation in small organizations (Campatelli et al., 2011);
investment in BEMs will usually need a few years before achieving a good return (Mann and Grigg, 2006); and
the lack of clarity about how culture can play a role in successfully implementing BEMs (Lasrado and Gomiscek, 2017).
Business excellence model implementation: success and failure factors
Many studies have identified factors contributing to the success or failure of BEM implementation efforts across various dimensions, such as country, industry, organizational type and size (Dahlgaard et al., 2013). Some researchers tend to agree that success in implementing business improvement initiatives depends more on management practices than on tools and techniques (Corbett and Angell, 2011). These practices may include a continuous commitment from top management, communication and trust, employee motivation, investment in resources, change management, performance management, a structured approach to solving problems and analysis standardization.
Other studies investigate factors that contributed most to a failure to implement BEMs. Ahire et al. (1995) and Soltani et al. (2005) identified the leading causes of failure as follows:
lack of top management commitment and engagement;
lack of vision clarity;
lack of adequate planning;
lack of necessary resources;
lack of change management;
high employee workload;
lack of sufficient training;
lack of focus on customers;
lack of performance measurement system; and
lack of engagement and empowerment for employees.
Business excellence model implementation in micro-, small- and medium-sized enterprises
Assarlind and Gremyr (2014) reviewed 59 studies to identify critical factors in quality management initiatives focusing mainly on SMEs. They identified factors in six major categories as follows:
gradual implementation using realistic goals;
contextualization;
involvement and training of employees;
management involvement;
involvement of external support; and
fact-based follow-up.
Similarly, Kharub and Sharma (2015) categorized 20 factors that drive the successful implementation of quality management practices in Indian SMEs (Table 1).
Sternad et al. (2017) classify the obstacles SMEs face when it comes to introducing BEMs into resource constraints concerning time and managerial and financial resources, and to attitudes and concerns such as doubts about the value of BEMs, bureaucracy, low level of transparency, limited feasibility and practice orientation.
Business excellence model implementation in the nonprofit sector
BEMs have received attention from NPOs globally mainly due to pressure from governments, donors and society to improve their performance (Claeye and Jackson, 2012). Ebrahim (2010) notes that in the USA, many state-sponsored nonprofit excellence associations have been established to improve NPOs’ effectiveness. Most of these associations have adopted the widely known “Standards of Excellence” developed by the Maryland Association of Nonprofits, which detail the requirements for NPOs to obtain excellence certification based on key dimensions that include governance, organizational integrity, communication with the public, finances, people management practices and public policy advocacy (Ebrahim, 2010).
Al-Tabbaa et al. (2013) addressed the applicability of BEMs for NPOs in the UK. They explore the extent to which quality models are appropriate for NPOs and find that the EFQM model is suitable for implementation in NPOs, self-assessment and planning improvements. They suggest a modified version of the original EFQM model to address the specific needs of the nonprofit sector.
Furthermore, Jevanesan et al. (2021) identified leadership, organizational culture and staff engagement as key implementation success factors in nonprofit organizations.
Excellence in the Gulf Cooperation Council region
BEMs have gained an increased focus in the Gulf Cooperation Council region in the 1990s, particularly in the UAE, with the launch of the Dubai Quality Award in 1992 (Lasrado and Gomiscek, 2017). The UAE Government’s focus on BEM implementation started in 1998 with the introduction of the Dubai Government Excellence Program and, subsequently, the nationwide excellence award, Sheikh Khalifa Government Excellence Program in 2015 (Carvalho et al., 2021).
Lasrado and Gomiscek (2017) reinforced the importance of the organizational culture in implementing BE in the UAE context. McAdam et al. (2013) concluded that there are major cultural differences to the extent that BEM implementation should take a different approach in the UAE. As an example of these differences, Lasrado (2019) found that the marketing and corporate image resulting from winning excellence awards is considered a key driver for implementing BEMs in UAE companies. Considering SMEs in the UAE, Rhys Rowland-Jones (2013) identified a strong need for leadership development among them, concluding that many of these SMEs cannot achieve the expected results, including adequate management systems and the enforcement of operational deadlines.
In Saudi Arabia, similar efforts have been made with the introduction of the King Abdulaziz Quality Award in March 2000 to foster quality and an excellence culture across all sectors. The award model, based mainly on the EFQM model, was revised and updated in 2015 to include five enablers and three results criteria (Nasseef, 2022).
Summary
This literature review shows that BEMs have been recognized as effective tools for improving performance across different organizational sectors while identifying many limitations affecting the use of BEMs in NPOs due to limited resources, including financial and human resources. Furthermore, while many studies have been done globally to investigate the impact of culture and organizational size on the implementation of BEMs in many countries, there is very little research covering the subject in the context of NPOs in Saudi Arabia in general and in micro NPOs characterized with limited human resources in particular. This research is intended to address this literature gap and develop a clear understanding of critical success factors and barriers to implementing BEMs in Saudi Arabia’s micro-NPOs. It also investigates the impact of human resources availability on BEM implementation in these organizations.
Methodology
This study aims to better understand the impact of human resources availability on BEM implementation among NPOs in Saudi Arabia. The study is designed to differentiate critical success factors and barriers to implementing BEMs among micro-NPOs in Saudi Arabia compared to larger NPOs. To define organizational size, we rely on the NPO’s workforce’s size, measured by the number of full-time employees. The study seeks to answer the following questions:
What are the key success factors impacting the successful implementation of BEMs among NPOs in Saudi Arabia? How are these success factors ranked?
What are the key barriers preventing NPOs in Saudi Arabia from implementing BEMs? How are these barriers ranked?
Are factors for successfully implementing BEMs in Saudi micro-NPOs and the barriers preventing the adoption of BEMs different from those affecting larger NPOs?
Given these questions, we selected a survey questionnaire as the strategy for conducting the study, as surveys are often associated with the deductive approach and can provide the quantity of data that can be useful in identifying possible relationships among variables (Saunders et al., 2009).
The questionnaire used in the study has five sections. Section 1 is designed to gather general information about the participating NPO and includes questions about the number of full-time employees, part-time employees and volunteers in the organization. Section 2 asks for demographic information about the respondents. Section 3 includes a question used to categorize survey respondents based on their experience in implementing BEMs. Respondents from NPOs that had not implemented any BEM initiatives in the 12 months before the survey date were directed to Section 4 of the questionnaire, which explored their perceptions of the criticality of barriers that prevented their organizations from implementing BEMs. Respondents from NPOs that had experienced BEM implementation initiatives over the past 12 months were directed to Section 5 to explore their perceptions regarding the criticality of factors impacting the successful implementation of those BEMs. The questions in Sections 4 and 5 were based on the literature review relevant to implementing BEMs and covered 15 implementation barriers and 36 success factors that were common across the literature.
The questionnaire was piloted with five participants representing the Committee for Nonprofit Organizations within the Saudi Quality Council. Two of the five members responded with feedback incorporated into the final version of the questionnaire.
Data collection
The study targeted more than 1,600 NPOs in 13 different administrative areas across Saudi Arabia. The total population sampling method was used as only 696 organizations could be reached through online surveying. Two hundred and thirty-six organizations responded to the survey, representing 33.9% of the invited organizations. Before analyzing the data collected from the questionnaires, responses were filtered to exclude the following:
responses from individuals who had spent less than one year in their organization; and
responses from individuals who are not at the managerial level.
After filtering the responses, the final data set included 138 responses, representing a 19.8% response rate, acceptable according to Neuman (2005), who indicated that a questionnaire’s response rate should be between 10% and 50%.
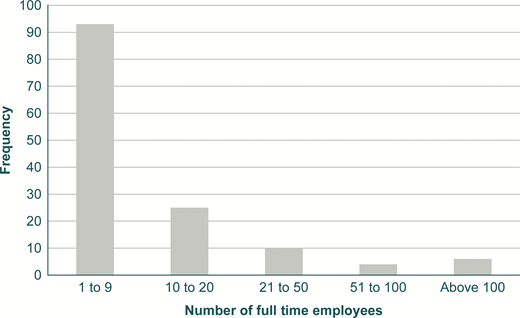
Of the 138 participating NPOs, over 67% (93 organizations) are considered micro-NPOs as they have one to nine full-time employees (see Figure 1).
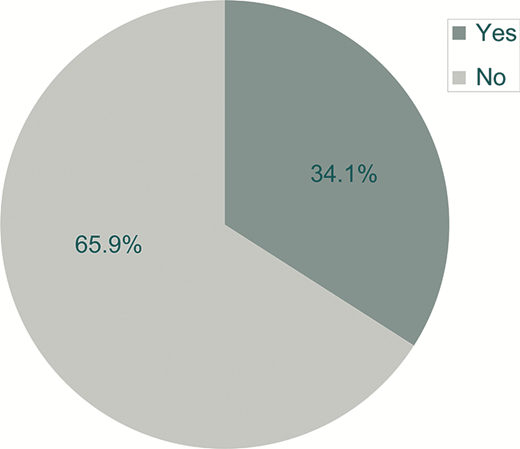
Figure 2 shows that of the 138 participating organizations, only 47 (34.1%) had implemented business excellence initiatives during the past 12 months.
To measure respondents’ views about the criticality of BEM implementation barriers, we used the following five-point Likert scale.
In Section 4, respondents indicated the criticality of barriers to implementing BE using the following scale:
Not a barrier
Not a barrier
Somewhat of a barrier
A barrier
A strong barrier
The answers were distributed as shown (Table 2):
In Section 5, respondents indicated the impact of the factors on the successful implementation of BE using the following scale:
Not impactful
Not impactful
Somewhat impactful
Impactful
Strongly Impactful
The responses from Section 5 were distributed as shown in Table 3:
Results
Validity and reliability of the data
The responses were divided into two data sets. The first set (D1) includes those respondents who answered “No” to the question, “Did the organization implement any BE initiative over the past 12 months?”; the second set (D2) consisted of questionnaires whose respondents answered “Yes.” After excluding incomplete responses, D1 contained 90 observations, and D2 had 42 observations.
The validity and reliability of the collected data were assessed based on the Pearson Product Moment Correlation that correlates each item’s scores with the total score using Statistical Package for the Social Sciences (SPSS, 2019). All p-values were found to be below the 5% significance level (α < 0.05), indicating the validity of the questionnaire for both success factors (Table 4) and barriers (Table 5).
We used Cronbach’s alpha to verify the reliability of the questionnaire and concluded that it is reliable, as shown in Table 6.
Ranking criticality of success factors and barriers
We conduct a factor analysis to define the criticality of each factor using the following algorithm:
we select the most critical factor as the one with the largest percentage of variance; then
we determined the criticality of each factor through the value of its coefficient in a linear combination to represent 1 for the first factor.
In data set D2 (success factors), the first factor explains 52.8% of the total variance. In Table 7, success factors are ranked by weight (criticality) with “Data analysis and reporting capabilities” defined as the most critical factor, with a coefficient of 0.858, and “Having a short implementation time” is the least critical factor, with a coefficient weight of 0.419.
For data set D1 (barriers), the first barrier explains 42.15% of the total variance. Table 8 shows that the most critical barrier is “Lack of a culture of continuous improvement,” with a coefficient of 0.798, and “Limited availability of financial resources” is the least critical barrier, with a coefficient of 0.268.
Impact analysis of human resources availability
To assess the impact of human resources availability on BEM implementation among NPOs, we conducted a Kruskal–Wallis nonparametric test to compare the answers for different groups. First, a new variable, “Group,” was introduced into data sets D1 and D2 according to the following rule: “Group” = 1 for organizations with one to nine full-time employees, and “Group” = 2 otherwise. Concerning the factors seen as critical to the successful implementation of a BEM, Table 9 shows no significant difference in the responses for NPOs with fewer than 10 full-time employees compared with responses from larger organizations, and the null hypothesis is accepted for every item.
When considering the barriers to implementing a BEM, the results in Table 10 show that the null hypothesis, “the distribution of responses is the same across NPOs grouped by the number of full-time employees,” is accepted for every item except for “Limited availability of financial resources” which differs between the two groups of respondents at a 5% significance level.
Discussion
Through this analysis, we identify the top five factors for successfully implementing a BEM among Saudi NPOs as follows:
data analysis and reporting capabilities;
effective organizational communication capabilities;
implementation strategy and approach;
use of benchmarking; and
adapting a clear governance framework.
We identify the top five critical barriers to implementing BEMs among NPOs in Saudi Arabia as follows:
lack of a culture of continuous improvement;
lack of organizational strategy;
lack of qualified employees;
lack of customer orientation; and
lack of clear organizational roles and responsibilities.
The results of this study are aligned with previous research reviewed in the literature in identifying management capabilities represented by data analysis and reporting, effective organizational communication and the culture of continuous improvement as the most critical factors when it comes to implementing BEMs in Saudi NPOs. However, unlike other studies on BEMs success and failure factors, the results ranked the adaption of a clear governance framework among the top critical success factors. This could be relevant to the Saudi nonprofit sector in particular due to the high enforcement of organizational governance matters through governmental regulations. The results also show that the availability of full-time employees in these organizations is not a significant element in determining BEM implementation success factors and barriers. This could be related to the fact that NPOs in Saudi Arabia rely heavily on volunteers and part-time employees when implementing BE initiatives, and as such, the impact of having full-time employees is minimized. Alternatively, it could be that the quality and capabilities of full-time employees are what really matter here rather than the count. The study reveals that the limited availability of financial resources is considered a critical barrier to implementing BEMs in micro NPOs compared to larger NPOs in Saudi Arabia. This could be because BEM implementation often comes with a high cost of implementation in small organizations (Campatelli et al., 2011).
The study presented in this paper relies only on quantitative methods, which can limit its findings. Accordingly, further studies using qualitative methods may be appropriate to verify and expand the findings of key success factors and barriers to implementing BEMs in micro NPOs in Saudi Arabia that can be further extended to other developed countries.